

China’s potential GDP growth
On Dec 12th, 2013, Professor Zhang Jun, director of the China Center for Economic Studies at Fudan University, made a speech of “China's potential GDP growth” in the 19th installment of “Hongru Forum”. By examining China’s total factor productivity (TFP), Prof. Zhang calculated China’s future potential GDP growth, and discussed how to learn lessons from Japan and the East Asian economies to avoid a low-growth rut.
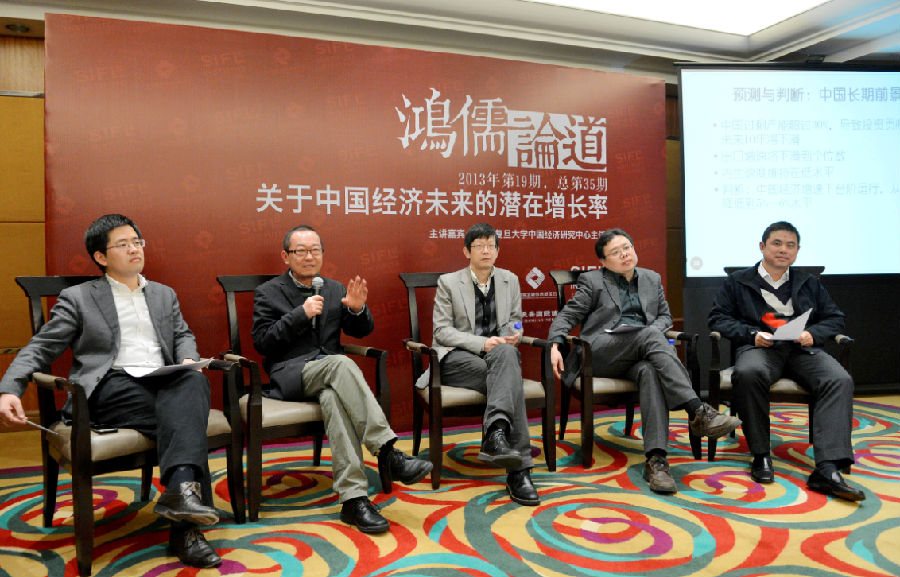
China has suffered an economic slowdown, from a nearly 10% annual output gain in 2007 to below 8% today, why? Prof. Zhang stated that the key is China’s decreasing TFP growth. The so-called TFP, which accounts for effects in total output not caused by traditionally measured inputs of labor and capital, often can be regarded as advances in technology and promotion in structure.
Why did China’s TFP growth decline? Because such an abnormal growth can’t be sustained now, Prof. Zhang pointed out. In the economic boom of the four “Asian Tigers”, the TFP growth didn’t exceed 2%; even in Japan, the number was not bigger than 3%, while China's TFP grows much greater. According to estimation of IMF, China's average TFP growth hits 3.8 during 1978-1993, and it still gain 3% during 1993-2005.
As TFP determines the marginal productivity of capital, the great increase of TFP led to the expansion of investment, and then made great contribution to China’s annual economic growth. Prof. Zhang took an example to demonstrate it. Though investment has soared by the 4 trillion yuan fiscal stimulus package, low capital productivity that determined by decreasing TFP can’t spur the economic growth. As a result, such a policy caused the high inflation.
According to the convergence hypothesis, although TFP growth decline is inevitable, it will not be a steep downward trend. Why did economies like Japan and South Korea experience sudden economic slowdown? Prof. Zhang believed it can be explained by external shocks. During Japan’s economic boom, its TFP contributed about 40% to GDP growth. When growth plummeted, TFP fell even faster – a dramatic change that was clearly linked to the 1971 yen appreciation and the 1973 oil crisis. Facing the demand shock followed the 2008 global financial crisis, China’s TFP has declined substantially.
To avoid falling into a low-growth rut in the long term, structural reform and industrial upgrading are urgently needed. In this sense, China’s government is facing an important test. If it fails to take advantage of the opportunity provided by the cost shock and economic slowdown to implement the necessary structural reforms, China’s potential growth rate, as dictated by TFP, will never rebound fully.
In Prof. Zhang’s opinion, the new round of structural reform should be aimed at creating conditions for economic transformation and upgrading. The key is to establish a level playing field guided by market rules, reduce government intervention in the economy, and stop protecting inefficient businesses. Such efforts would go a long way toward increasing China’s potential growth rate. Aided by structural reforms, China’s economy could expand even faster, achieving 7-8% annual growth over the next ten years.
“Hongru Forum” is a public seminar jointly launched by Liu Hongru Financial Education Foundation and SIFL Institute, and is held regularly once in two weeks. The seminar pays attention to various issues in China’s finance and macro-economy, and devotes itself to building a platform for cross boundary exchanges among excellent scholars, government and market institutions.
Since August 2013, “Hongru Forum” has gained the exclusive support of Chang’An International Trust Co., Ltd.


